Have you ever seen a brokered CD offering a better rate than your bank and thought, “Isn’t this basically the same CD, only better?” That is the question worth asking before looking at the yield.
A brokered CD is a certificate of deposit bought through a brokerage rather than opened directly with one bank. The rate may look attractive, and comparing several issuers in one account is convenient. But the exit works differently. If you need your money before maturity, you may have to sell the CD in a secondary market, where its price can be below what you paid.
In plain language, a traditional bank CD often charges an early-withdrawal penalty. A brokered CD may instead give you a market price. Those two outcomes are not the same. A higher displayed rate is useful only if the issuing bank, insurance coverage, maturity, call terms, and access to your money all fit your plan.
Key Takeaways
- Brokered CDs are bank deposits purchased through an intermediary, usually a brokerage firm.
- They may provide access to multiple issuing banks and a wider range of maturities from one account.
- FDIC coverage depends on the issuing bank, ownership category, and your total deposits at that same bank—not the brokerage name alone.
- If you sell before maturity, the price can be below what you paid, especially after market rates rise.
- Callable features, accrued interest, settlement timing, and secondary-market liquidity deserve review before purchase.
What Are Brokered CDs?
A traditional CD is opened directly with a bank. You deposit a fixed amount for a stated term, the bank pays interest under the agreement, and the CD returns principal at maturity. With brokered CDs, a brokerage or another deposit broker places or distributes deposits from one or more issuing banks to customers.
The brokerage is the storefront, but the issuing bank is the institution that owes the deposit. That distinction affects deposit-insurance calculations. It also means a saver should record the name of every issuing bank instead of treating all positions on one brokerage screen as one institution.
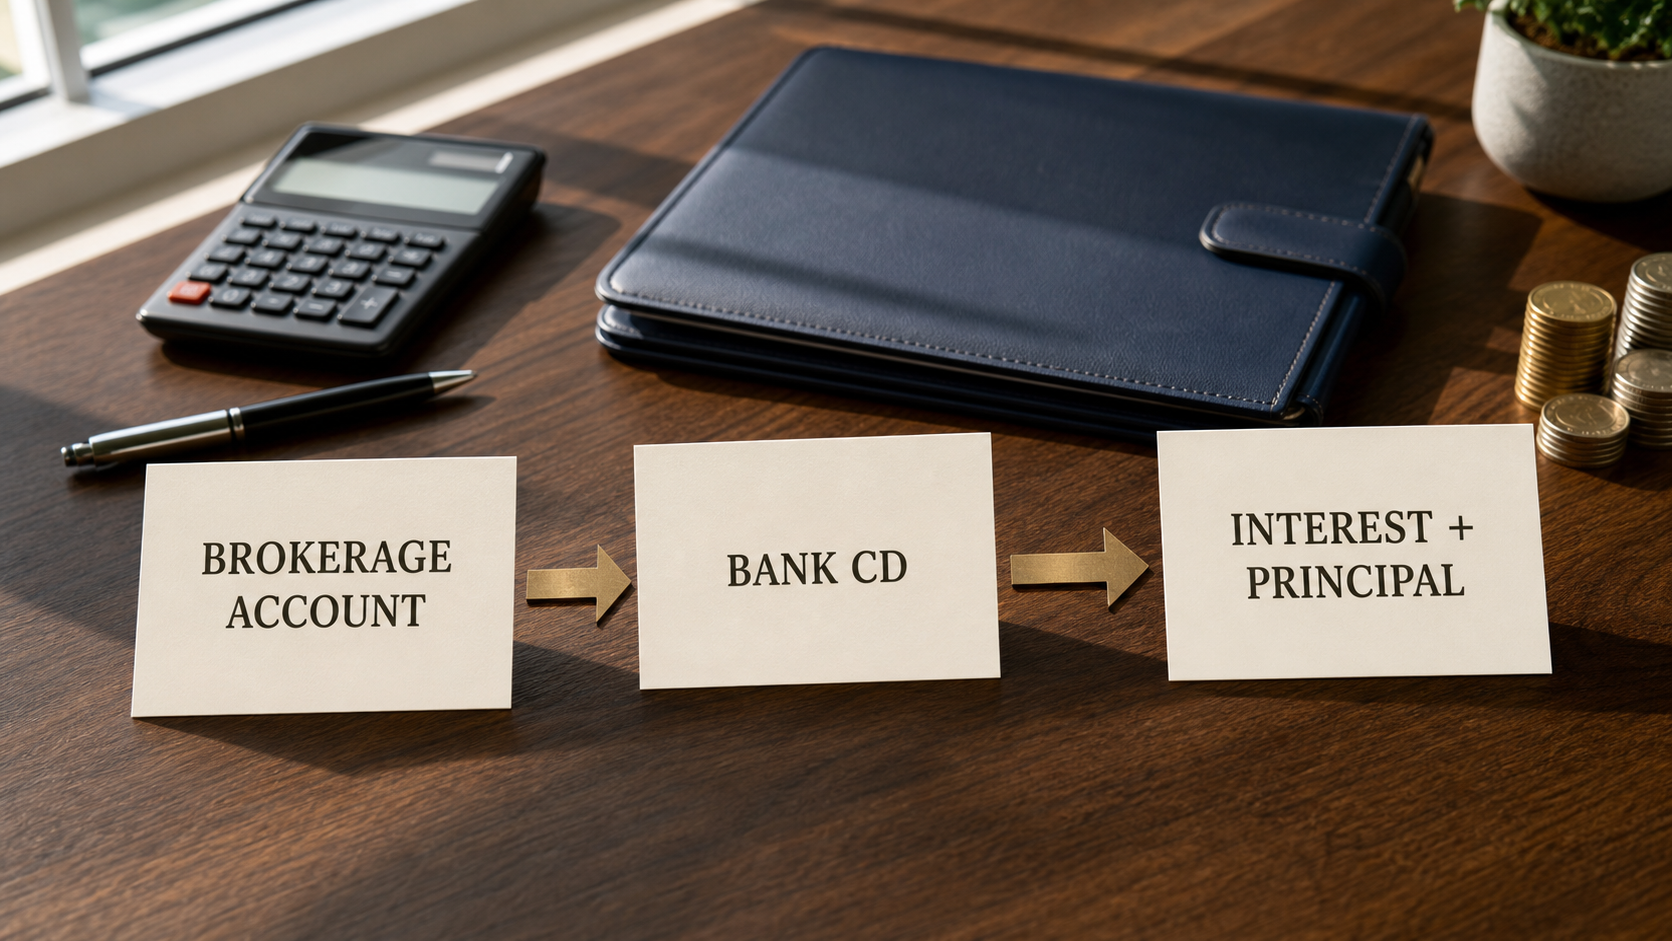
The SEC explains that many offerings are interests in a larger master CD issued to a deposit broker. Customers generally see the position inside their brokerage account, receive interest according to its terms, and receive principal when it matures, assuming the issuing bank meets its obligation.
This structure should not be confused with a money market fund, which is an investment fund, or a Treasury bill, which is a U.S. government obligation. Each product has a different issuer, protection structure, liquidity profile, and tax treatment.
How Brokered CDs Work
A brokerage platform may display new-issue CDs from several banks. The investor selects an issuer, maturity, quantity, and rate. Many new issues are sold in standard increments, and the brokerage records the position after settlement.
A new-issue CD is generally purchased at its offering terms. A secondary-market CD is being resold by another holder and may trade above or below its original value. The quoted yield may reflect the current purchase price rather than only the stated coupon.
At maturity, principal and final interest normally arrive in the brokerage account. The investor can withdraw the cash or make a new decision. Some brokerage settings may permit automatic reinvestment, but investors should never assume that a replacement will have the same bank, rate, term, or insurance status.
Building several maturities can resemble the strategy described in GSV’s CD ladder guide. For example, money can be divided among six-month, one-year, and two-year maturities. The benefit is scheduled access; the tradeoff is that part of the cash remains committed if needs change.
Potential Advantages of Brokered CDs
More Banks in One Account
A brokerage can make comparison easier by listing CDs from multiple institutions on one screen. That may reduce the need to open and manage a separate online account at every bank. Convenience does not eliminate the need to verify each issuer and its terms.
Rate and Maturity Choice
Some issuing banks use brokerage networks to reach a large pool of deposits. The resulting menu can include short and long maturities that are unavailable at a local bank. A broader list helps investors match cash flows to tuition, a home purchase, retirement spending, or another dated goal.
Potential Secondary-Market Access
Traditional bank CDs commonly allow early withdrawal for a stated penalty. Brokered CDs often rely instead on a secondary market when an investor wants to exit. The ability to offer a position for sale can be useful, but it is not guaranteed liquidity or principal protection.
Fixed Cash-Flow Planning
A known maturity and stated interest schedule can support short-term planning. This is especially valuable for money that should not face stock-market volatility. Compare the commitment with the liquid reserve described in GSV’s emergency fund guide.
Brokered CD Risks Investors Can Miss
Market Loss When Selling Early
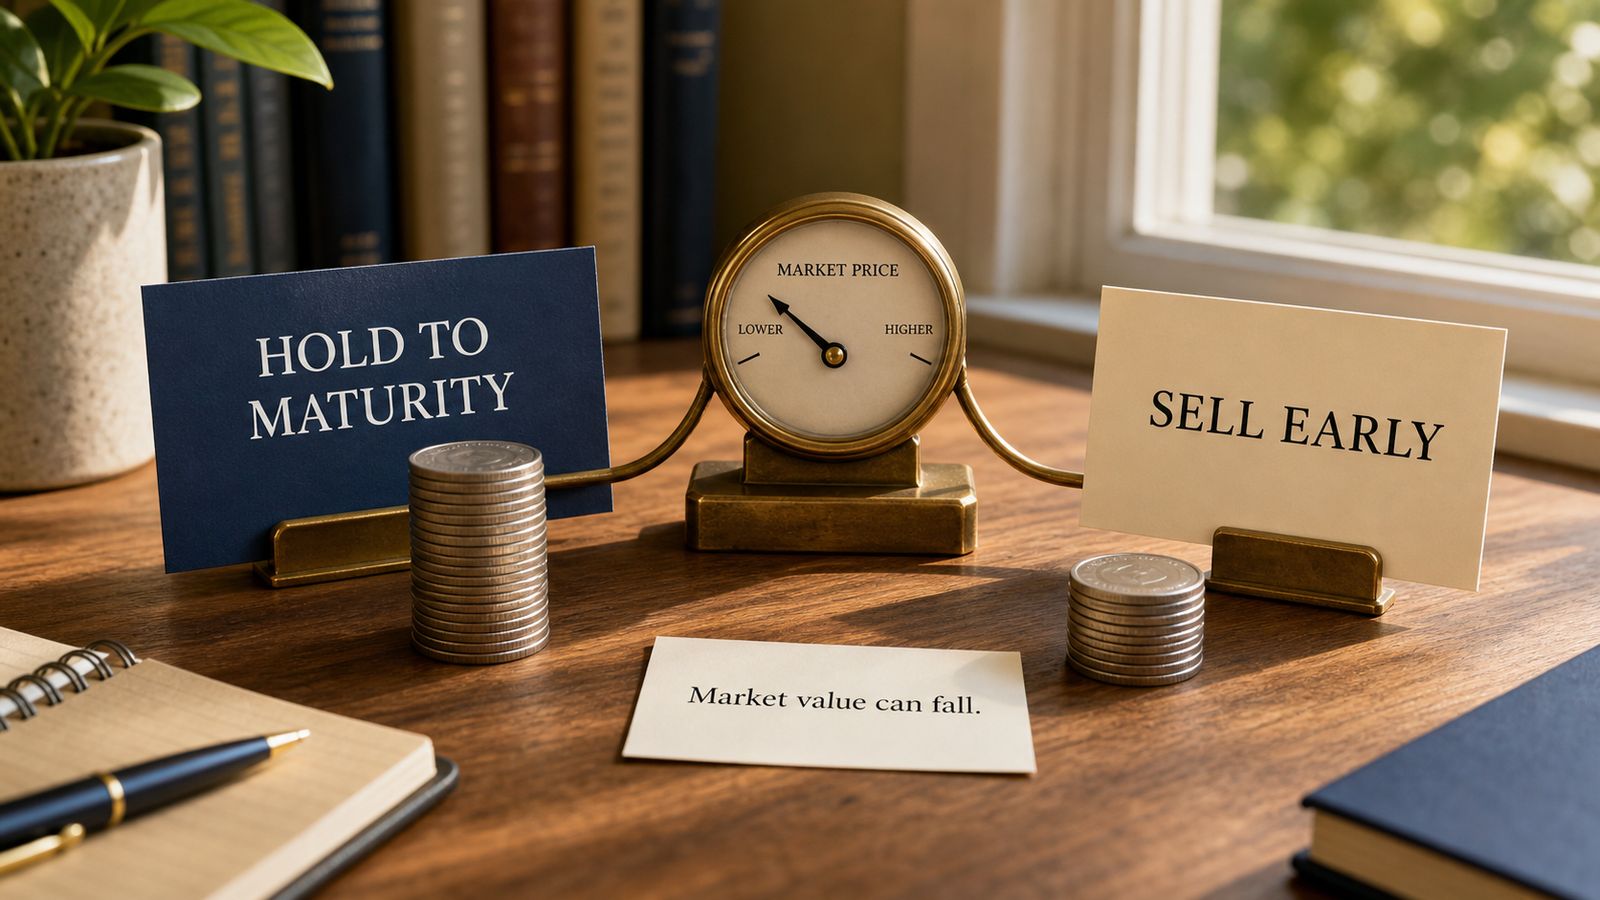
If interest rates rise after purchase, newer CDs may pay more. An older lower-rate position can become less attractive, so a buyer may offer less than its face amount. Selling before maturity can therefore create a capital loss. Longer remaining maturities generally create more rate sensitivity, similar to the mechanics in GSV’s bond duration guide.
If rates fall, an existing higher-rate position may gain value, but there is no assurance that the secondary market will be deep or that the bid will be favorable. A brokerage may also charge a transaction fee or include compensation in the price.
FDIC Limits Can Overlap
FDIC insurance generally covers eligible deposits up to at least $250,000 per depositor, per insured bank, for each ownership category. Principal and accrued interest count toward the limit. If you already hold savings, checking, or CDs at the same bank, a new brokered position may push the combined amount above coverage.
Different branches of the same bank do not create separate limits. Different legally chartered insured banks may. The FDIC’s BankFind and Electronic Deposit Insurance Estimator are the appropriate tools for checking the institution and estimating coverage.
Callable CD Risk
Some long-term or high-rate offerings are callable. The issuing bank can redeem them on specified dates, usually when doing so benefits the bank. If rates fall, the investor may receive principal back earlier than expected and have to reinvest at lower available rates.
Do not compare a callable rate with a noncallable rate as though the promises are identical. Read the first call date, subsequent call schedule, and whether the return calculation assumes the CD lasts to final maturity.
Broker and Recordkeeping Risk
The FDIC warns that a buyer using a third-party broker relies on that broker to place the funds and maintain records correctly. Deposit insurance attaches to an eligible deposit at an insured bank; it does not make every product with “CD” in its name insured.
Inflation and Opportunity Cost
A fixed rate can lose purchasing power if inflation remains higher than expected. It can also become unattractive if market rates rise. A safe nominal return is not the same as a guaranteed real return. Review the relationship in GSV’s CPI guide.
Brokered CD vs Traditional Bank CD
| Feature | Brokered CD | Direct Bank CD |
|---|---|---|
| Where purchased | Brokerage or deposit broker | Directly from one bank |
| Issuer selection | Often multiple banks | That bank’s offerings |
| Early exit | Usually secondary-market sale | Usually withdrawal penalty |
| Value before maturity | Can trade above or below principal | Usually displayed at deposit amount |
| Call feature | Available on some issues | Less common in basic retail CDs |
| FDIC review | Track each issuing bank | Track total deposits at that bank |
Neither format is universally better. A direct bank CD may be simpler when the early-withdrawal penalty is clear and the saver values direct service. Brokered CDs may suit an investor who wants to compare several issuers, schedule maturities, and hold each position until it ends.
A high-yield savings account may be more appropriate for money that must remain accessible, although its APY can change. For brokerage cash that needs daily liquidity, understand the differences among bank sweeps and funds rather than assuming they share the same insurance.
What to Check Before Buying
- Identify the issuing bank. Confirm it through FDIC BankFind, not just the product description.
- Add all deposits at that bank. Include principal and accrued interest held directly or through other brokerages in the same ownership category.
- Read the maturity and settlement dates. Make sure the cash schedule matches the goal.
- Check whether it is callable. Review the first call date and the reinvestment risk.
- Understand interest payments. Note the coupon, payment frequency, and whether the quoted yield assumes a particular price.
- Review the early-sale process. Ask whether a secondary market exists, how pricing works, and which fees apply.
- Check for survivor options. Some CDs allow an estate to redeem at face value after the owner’s death, but rules and limits vary.
- Avoid using emergency cash. A future buyer may not offer the amount you need on the day you need it.
Position size should fit the goal rather than the most attractive advertised rate. Diversifying across maturities and issuers can help manage timing and insurance concentration, but it does not remove inflation or reinvestment risk. GSV’s diversification guide explains why spreading exposure must be purposeful.
Official Sources
- Investor.gov: Brokered CDs Investor Bulletin
- FDIC: Shopping for a Certificate of Deposit
- FDIC: Deposit Insurance
- FINRA: Bank Products
Final Thoughts
Brokered CDs are not bad products. They are products that punish a casual assumption: “CD means my principal is always easy to get back.” If you can hold to maturity and the insurance details are clear, the structure may be useful. If the money might be needed suddenly, the higher rate may not be worth the loss of flexibility.
Before buying, write down the issuing bank, maturity date, call terms, interest schedule, FDIC overlap, and what would happen if you sold early. If any one of those answers is unclear, pause. A few extra minutes of checking can matter more than a small difference in yield.
Frequently Asked Questions
Are brokered CDs FDIC insured?
Eligible CDs issued by an FDIC-insured bank can receive pass-through coverage when requirements and records are satisfied. Coverage is subject to the standard limit by depositor, insured bank, and ownership category.
Can I lose money on a brokered CD?
You can receive less than principal if you sell before maturity at an unfavorable market price. Amounts above applicable insurance limits can also be at risk if the issuing bank fails.
Why can brokered CDs pay higher rates?
Banks may use brokerage networks to gather deposits efficiently, and some offerings compensate investors for longer terms or features such as callability. A higher rate may therefore come with different conditions.
What happens when a brokered CD matures?
Principal and final interest generally settle as cash in the brokerage account. Reinvestment is a new decision and may occur at a different rate.
Continue Learning
Compare the other major choices for short-term money.
Educational disclaimer: This article is for general educational purposes only and is not personalized financial, tax, or legal advice. Product terms, rates, insurance eligibility, market prices, and brokerage policies can change. Verify current disclosures and consider your liquidity needs and risk tolerance.